01
Sell fast, as-is
Get a cash offer in writing and close on your timeline. Leave the home just as it is.
- No repairs or fix-ups
- No showings or open houses
- No fees or agent commissions
- You pick the closing date
- No obligation to accept
Washington State · Portland, OR
Based in Kennewick, helping Northwest homeowners
Most homeowners have more options than they realize. The sooner they understand them, the more they have to choose from.
Behind on payments, or holding a house you need to be done with? Hope4Homes NW is locally owned, right here in Kennewick. Tell us what's going on. We'll be honest about every path, including the ones that don't involve us.
No showings. No fees. No repairs. No obligation to sell.
If the letters have started
Maybe a quick cash sale is the right fit. Maybe it's a more flexible arrangement. Maybe selling isn't right at all. We'll help you see the whole picture first. Then you decide. No judgment, no pressure, no hard sell.
We help people who are:
How we help
We don't walk in with one offer and a pen. We start with where you are and what you want, and we work forward from there.
Get a cash offer in writing and close on your timeline. Leave the home just as it is.
When a cash offer doesn't fit, we can get flexible. A few ways that can look:
Each one has trade-offs. We'll explain them plainly, put everything in writing, and encourage you to have an attorney review it.
Selling isn't always the right option. When it isn't, we'll tell you so, and we'll point you in the right direction.
Call, text, or send the form. No paperwork needed to start.
Your home, your timeline, any dates on your notices, and what you want.
If an offer fits, you get it in writing and time to think it over.
The Washington process
Most Washington home foreclosures happen outside of court, through a trustee. This is the general order of events for an owner-occupied home. Your dates may differ, so always go by the letters you receive.
Once you fall behind, your servicer will call and send letters. Late fees start adding up.
Before starting foreclosure, your lender has to try to reach you and offer a chance to meet and talk about alternatives. The letter tells you how long you have to respond. Responding buys you more time to work things out before the next step.
This is the formal start of the foreclosure. It says how much is past due and who to contact. It also lists housing counseling resources.
At least 30 days after the Notice of Default, the trustee can record a Notice of Trustee's Sale. It sets the auction date, which is generally at least 90 days later. Washington law also says the sale can't happen sooner than 190 days after the date you first defaulted.
The home is sold to the highest bidder, usually at a public place like the county courthouse. After the sale, the new owner can take steps to have you move out.
Washington's Foreclosure Fairness Act created a mediation program. It gives you a formal meeting with your lender and a neutral mediator to look for a way to avoid foreclosure. Both sides have to take part in good faith and share certain documents.
You can't sign up on your own. A HUD-approved housing counselor or an attorney has to refer you. The referral can happen any time after a Notice of Default is issued, but generally no later than 90 days before the sale date. Some smaller banks and credit unions are exempt. Because of the deadline, it helps to talk with a counselor early.
To find a counselor, visit hud.gov/findacounselor or call (800) 569-4287. The Washington State Department of Commerce runs the mediation program and has more information on its website.
Live in Oregon? Oregon's process and timelines are different. A local housing counselor can walk you through them, and we're happy to talk too.
This is general information, not legal advice. Laws change, and your situation may have details that matter.
My story
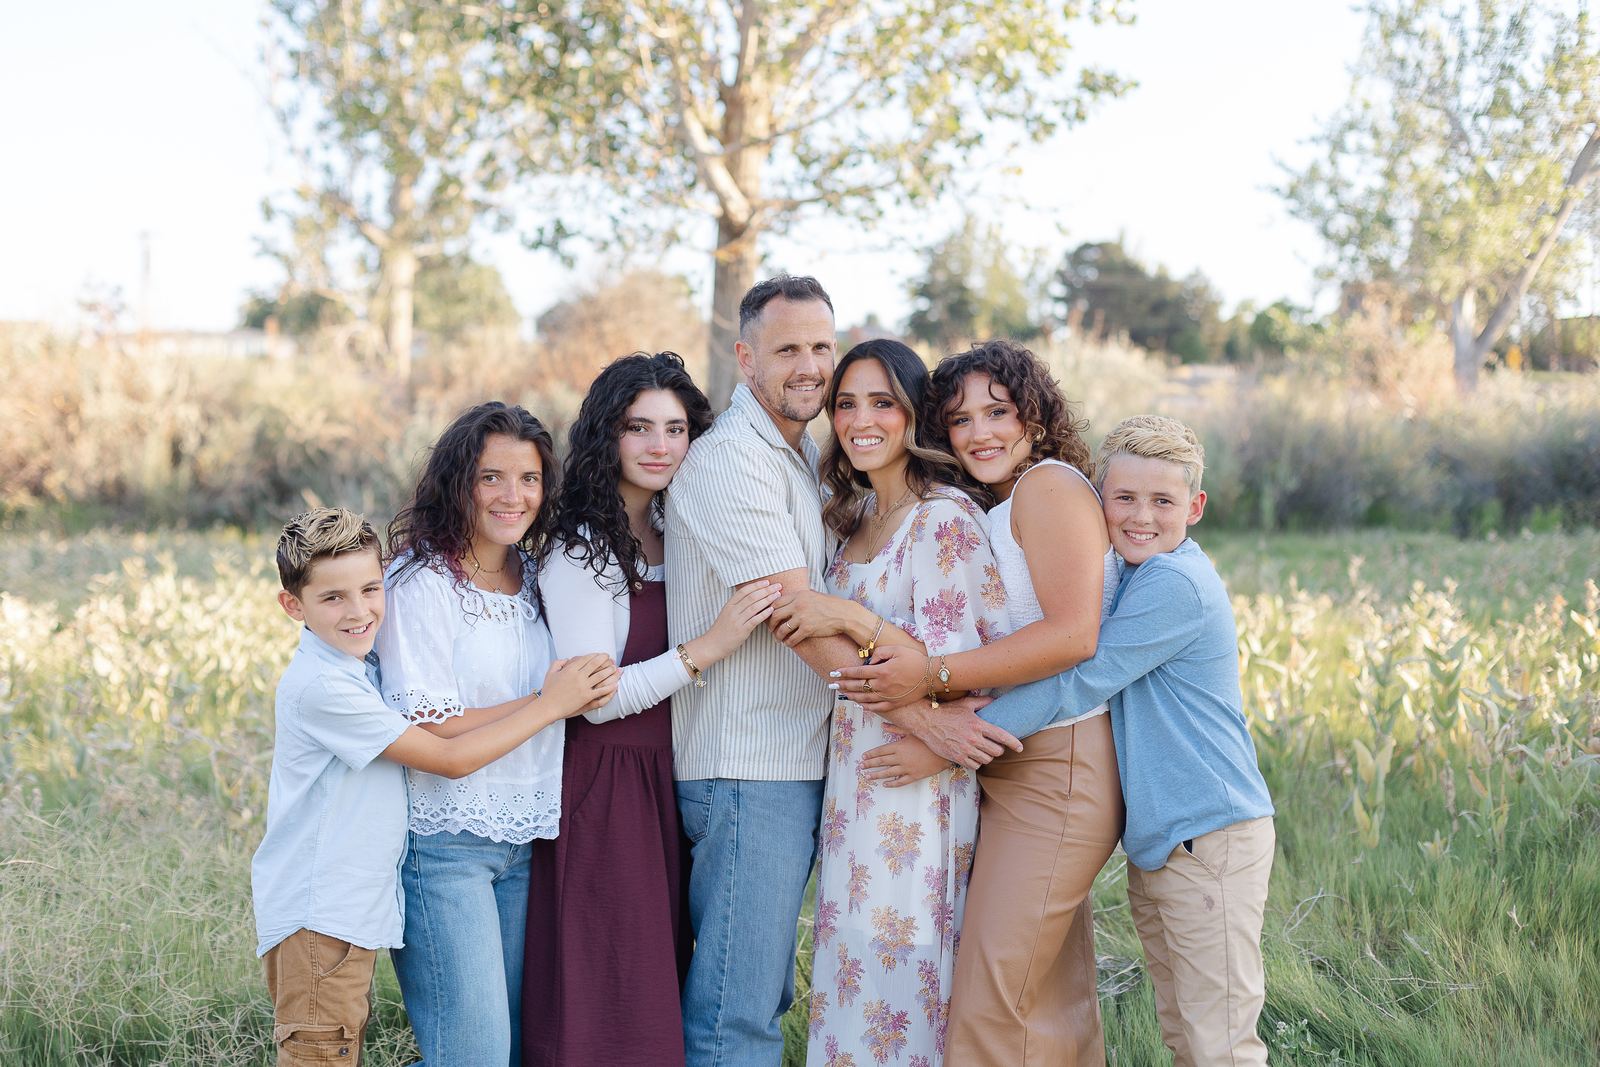
Hope4Homes NW is me, Kevin, a real estate investor in Kennewick, Washington. I'm also a nurse. That's my day job. I enjoy caring for people holistically, and I bring that same care to homeowners facing foreclosure.
This work is personal. I have seen the many struggles that homeowners face when met with foreclosure. I have a great desire to help walk these homeowners through all their options so they can make informed decisions about one of their most valuable assets.
I'm one person, not a national company or a sign stapled to a telephone pole. When you call, you get me. I'll learn your story and give you a straight answer.
I have 5 children. They are my life. They're the reason I want to help others.
Areas we serve
Home base is Kennewick. We also help homeowners in Yakima, Seattle, Spokane, and Vancouver, and across the river in the Portland area.
Somewhere else? Get in touch anyway. If we can't help, we'll try to find someone who can.
Common questions
Not always. Some paths can still work close to the sale date, but they take time to set up. Reach out today and we'll look at what's realistic.
You tell us about the home. We look at it and give you a cash offer in writing. If you accept, you pick the closing date. You don't need to make repairs or hold showings first.
They're ways to sell when a straight cash sale doesn't fit, like subject-to, wraps, or equity partnerships. Each one has trade-offs. We'll explain them in plain English and put everything in writing. We encourage you to have an attorney review any agreement before you sign.
No. Talking with us is free, and there's never an obligation to sell. If an offer doesn't feel right, you can say no.
No. We will never ask you for money up front, and you should be careful with anyone who does.
We're investors. When it makes sense for both sides, we buy homes, and we earn money when we later sell or rent them. We'll be upfront about that from the first call.
Equity is roughly what your home is worth minus what you owe. For example, if a home is worth $350,000 and the loan balance is $250,000, the equity is about $100,000 before selling costs. At a foreclosure auction, homes often sell for less than they're worth, and much of that equity can be lost.
Yes. We don't sell or share your information. We only use it to talk with you about your situation.
Yes, it's a good idea. A HUD-approved housing counselor can often help for free, and an attorney can explain your legal rights. We're glad to talk with you either way.
Talk to us
Call, text, email, or send a quick note. No obligation and no sales pitch. Just an honest conversation about your situation and your options.
Call or text anytime and we'll get back to you.